


Updated October 2026 · By Sara Marsden-Ille
Retirement is the era of the “Silver Tsunami“—a time when more baby boomers than ever are taking to the skies, seas, and open roads to celebrate their hard-earned freedom. Whether it’s a Mediterranean cruise or a slow trek through the Rockies, the world is more accessible than ever. However, traveling in your 60s and beyond requires a different kind of preparation.
While most of us remember to pack our medications and double-check our passports, there is one critical item often left off the list: a plan for the unthinkable. It sounds somber, but being prepared is the ultimate act of love for your family.
A one-time payment of $450 today can protect your family from financial burden and save them from unexpected costs that commonly run $3,000 to $7,000 within the U.S., and regularly exceed $15,000 from abroad. If you want to achieve easy reassurance for less than a set of tires, you need to look beyond standard travel insurance.
Let’s explore why you should consider this low-cost travel protection now, what gaps exist in standard travel insurance, and what devastating costs your family could face if the unthinkable did happen when you were traveling.
1. The Gap in Standard Travel Insurance

Most travelers believe they are fully covered because they purchased a standard travel medical policy. While these policies are excellent for hospital stays, broken bones, or emergency evacuations, they have a “hidden” expiration point.
When a policyholder dies, medical coverage ends. Any benefit to bring the person home is usually capped and conditional, which can leave the logistics, and any cost above the cap, with the grieving family.
Many families assume their travel policy will cover every repatriation expense, and often it won’t. Medicare and credit card travel cover generally don’t extend to repatriation costs either. If a relative at home dies while you’re away, that’s a different part of the policy; see does travel insurance cover a death in the family.
Repatriation of remains—the process of bringing a body home across state or national lines—is a complex legal and bureaucratic maze. It involves:
- Dealing with foreign consulates and death certificates.
- Specialized transportation requirements, such as airline-approved shipping containers.
- Navigating different funeral laws in every jurisdiction.
Without a dedicated travel protection plan, your family could be left stranded in a foreign country or across the coast, trying to navigate these hurdles while facing a massive bill.
2. Understanding Repatriation and Death Expense Costs
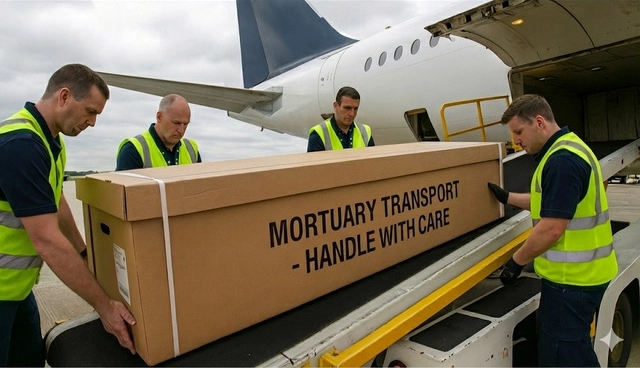
Why is this so expensive? If a death occurs away from home, the costs are not just “funeral costs”—they are “transportation plus funeral costs.”
- Distance Matters: If you are more than 75 miles from home, your local funeral home usually can’t simply drive over to bring you back.
- The real cost: Between transportation, specialized containers required by airlines, and the fees charged by two different funeral homes (one at the location of death and one at home), bringing someone home within the U.S. commonly costs $3,000 to $7,000. International repatriation regularly exceeds $15,000.
- The Risk Factor: Statistically, as we age, the risk of a health event while traveling increases. While we all hope for a smooth trip, the “elevated risk” for senior travelers makes having a dedicated plan essential.
By securing a lifetime travel protection plan, you ensure that these costs are handled by professionals. It’s about moving the logistical weight from your children’s shoulders to a dedicated service provider.

Would your kids be emotionally, or financially, capable of navigating the complexity of a death overseas, liaising with embassies, or wiring thousands of dollars to a foreign funeral service provider?
We all think it will never happen to us. But when it does, a family faces decisions, paperwork and a bill all at once. Get your Travel Plan set up today, and enjoy peace of mind on every trip.
3. Essential Travel Pre-Departure Checklist for the Over-60s.
Before you lock the front door, ensure these four pillars of senior travel are in place:
- Medical Documentation: Carry a physical list of all medications, dosages, and your primary physician’s contact information.
- Legal Accessibility: Ensure your Power of Attorney and healthcare proxy documents are digitized and accessible to your emergency contacts.
- Communication Plan: Set up an international “check-in” schedule. If your family knows your itinerary, they can respond more quickly in an emergency.
- Repatriation Protection: Have a plan that brings you home from anywhere in the U.S. or overseas once you are 75 miles or more from your legal U.S. residence, with a 24/7 assistance number your family can call. Enroll while you’re at home: if you enroll while away, the plan takes effect only once you return.
4. A Simple & Affordable Travel Protection Plan is Your Peace of Mind for a Lifetime

The beauty of modern travel protection plans is that they are often a one-time enrollment. You don’t have to remember to “buy” it every time you take a trip. It is a permanent safety net that stays with you.
One payment of $450 for an individual, or $875 for a couple, covers you for life, with no renewals and no age limit. It allows you to enjoy your cruise or your road trip with the quiet confidence that you have handled the “what ifs.”
Heading away this winter (2026–27)? Three dates and rules to know
- Medicare Open Enrollment runs October 15 to December 7. You can join, drop or switch Medicare Advantage and drug plans, and changes start January 1 (Medicare.gov). If you’ll winter outside the U.S., read what Medicare doesn’t cover when you travel.
- The 180-day rule. The plan covers stays of up to 180 days in any 12-month period at another address. Stay longer, and that address is treated as your legal residence.
- Enroll before you go. If you enroll while away from your U.S. home, the plan takes effect only once you return.
For the full list, see The Senior Traveler’s Complete Protection Checklist. Snowbirds can also read snowbird travel insurance: what it covers, and anyone wintering south of the border what happens if you die in Mexico.
ACT NOW: Don’t Leave Home Without This Travel Protection
Traveling in your 60s should be about joy, discovery, and the wind in your hair—not about worrying over fine-print insurance loopholes. The reality of the “Silver Tsunami” means we are traveling further and staying away longer.
By addressing the importance of death and repatriation coverage now, you are ensuring your legacy is one of adventure, not a financial burden for your heirs.
Don’t leave home without this travel protection. It is the most practical, affordable, and selfless gift you can give your family before your next departure.
Ready to secure your next adventure?
Enroll in the Travel Plan today: Never worry about the ‘What If” again. Give your family the gift of knowing you will always get home.
I have been researching and writing about the death care industry for the past 18 years. End-of-life services and experiences are topics most people avoid thinking about until they must face them. My work provides comprehensive and independent resources for families, explaining the workings of the funeral industry, the laws governing funeral practices, and the death care trends that impact consumers. With a BA in Cultural Studies, I bring a unique perspective to analyzing cultural death care rituals, complemented by a career background in Business Management. The death care industry is undergoing significant changes, which I find fascinating. The shift towards cremation services and the emergence of sustainable alternatives like aquamation and human composting are of particular interest. I am also intrigued by how technology is reshaping the funeral planning process and experience. I write for US Funerals Online and DFS Memorials LLC, and contribute to various forums and publications within the death care industry.
